
Construction Loan Interest Worked Through: How Progress Draws Change What You Pay
ADS Team
Author
November 6, 2026
about 8 hours ago
5
views
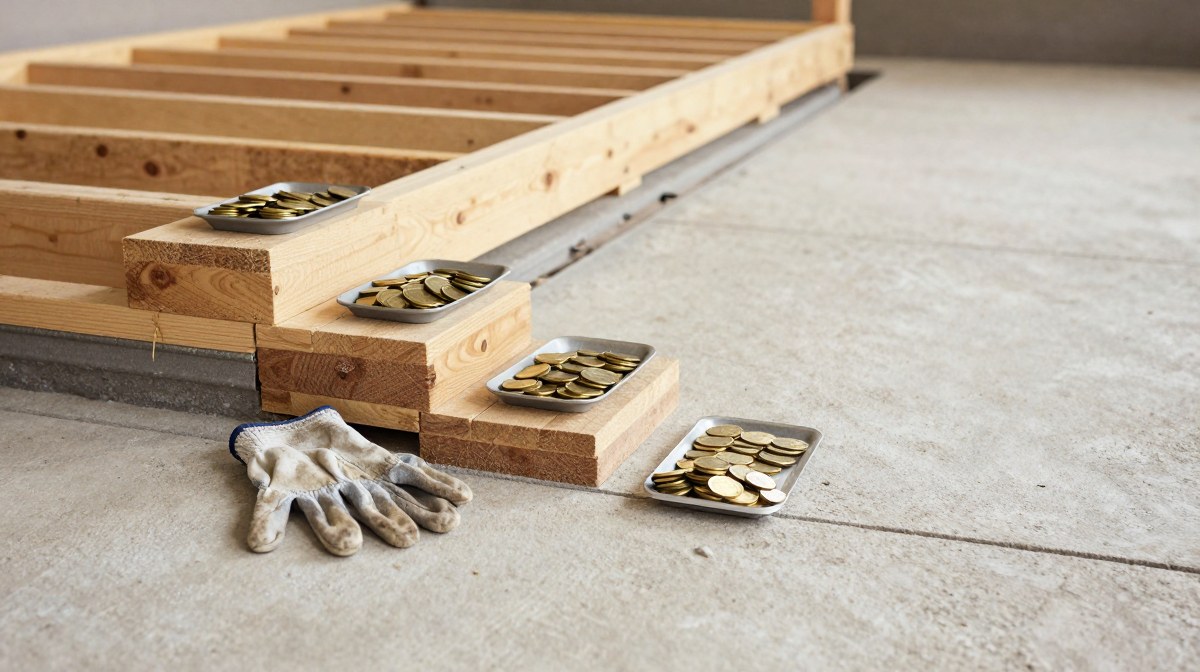
In short: On a construction loan you pay interest only on what has been drawn, so the bill starts small and climbs at each stage. In our illustrative example - a $300,000 land loan plus a $600,000 fixed-price build at an example rate of 7.0% - interest over an 11-month build totals $36,575, against $57,750 if the full $900,000 were drawn on day one. At completion the loan usually switches to principal and interest, and the repayment steps up.
Key takeaways
- Interest is charged on the drawn balance only, usually calculated daily and charged monthly.
- In the example, monthly interest rises from $1,925 after the deposit draw to $5,250 at completion.
- Switching to principal and interest at completion adds about $738 a month to the example repayment.
- Capitalising interest instead of paying it adds interest on interest: about $882 in the example.
- A three-month delay at frame stage costs $9,450 in extra interest in the example, before rent.
- The RBA cash rate target was 4.60% from 30 September 2026; check the current target before relying on any rate.
How is interest charged on a construction loan?
A construction loan is set up with a limit equal to the land debt plus the build cost, but the build money is released in stages as the builder reaches each milestone. Interest runs only on the amount actually drawn. Lenders generally calculate it daily on the outstanding balance and charge it monthly, as our explainer on daily interest accrual shows. The examples below use simple monthly figures so the arithmetic stays visible.
During the build, most residential construction loans are interest-only. Once the house reaches practical completion and the final draw is paid, the loan converts to principal and interest (P&I) over the remaining term, unless you have arranged a further interest-only period.
Two things set the size of the bill: how much is drawn, and for how long. The draw amounts come from the building contract's progress payment schedule; the timing comes from the builder.
What are the assumptions in the worked example?
For illustration only - an example, not an offer, and not any lender's rate or policy. You own a block with a $300,000 loan on it, rolled into the construction loan at the start. You sign a $600,000 fixed-price contract with an 11-month build. The example rate is 7.0% a year, variable, interest-only during construction.
| Stage | Share of contract | Draw | Month paid |
|---|---|---|---|
| Deposit | 5% | $30,000 | 0 |
| Base (slab) | 15% | $90,000 | 2 |
| Frame | 20% | $120,000 | 4 |
| Lock-up | 25% | $150,000 | 6 |
| Fixing | 20% | $120,000 | 9 |
| Practical completion | 15% | $90,000 | 11 |
| Total | 100% | $600,000 |
Stage percentages differ between contracts and states. Use the ones in your own contract when you run the construction progress draw calculator.
How much interest do you pay at each stage?
| Period | Drawn balance (land + build) | Monthly interest at 7.0% | Months | Interest for the period |
|---|---|---|---|---|
| Months 0-2, after the deposit | $330,000 | $1,925 | 2 | $3,850 |
| Months 2-4, after base | $420,000 | $2,450 | 2 | $4,900 |
| Months 4-6, after frame | $540,000 | $3,150 | 2 | $6,300 |
| Months 6-9, after lock-up | $690,000 | $4,025 | 3 | $12,075 |
| Months 9-11, after fixing | $810,000 | $4,725 | 2 | $9,450 |
| Total during the build | 11 | $36,575 |
Each monthly figure is the balance times 7.0% divided by 12: $330,000 × 0.07 ÷ 12 = $1,925, and so on down the table. Of the $36,575, $19,250 is interest on the $300,000 land loan ($1,750 a month for 11 months) and $17,325 is interest on the build draws.
Had the full $900,000 been drawn on day one, 11 months of interest would be $57,750. Staged drawing saves $21,175 in this example, which is why construction loans release money in stages rather than as one lump sum.
A useful way to read the result: $36,575 of interest at 7.0% over 11 months is what an average balance of $570,000 would cost ($570,000 × 0.07 × 11 ÷ 12 = $36,575). Over the build you carried, on average, about 63% of the $900,000 limit. Use that ratio to sense-check a lender's or builder's estimate of interest during construction: if it implies the full limit is drawn from the start, it is overstated; if it implies almost nothing is drawn until the end, it is understated.
The heaviest months come late. Lock-up to fixing is the longest stage here and carries the largest period of interest, $12,075, because the balance is already $690,000.
What happens to repayments at completion?
At practical completion the final $90,000 is drawn and the balance reaches $900,000. Interest-only at 7.0% would be $5,250 a month. Converted to P&I over 30 years at the same example rate, the repayment is about $5,988 a month, roughly $738 more. Some lenders run the P&I term from completion; others count the construction months as part of the term, which makes the P&I repayment slightly higher. Check the figure for your own numbers with Moneysmart's mortgage calculator.
| Point in the build | Balance | Monthly payment (example 7.0%) |
|---|---|---|
| After the deposit draw | $330,000 | $1,925 interest-only |
| After lock-up | $690,000 | $4,025 interest-only |
| At completion, interest-only | $900,000 | $5,250 |
| At completion, P&I over 30 years | $900,000 | About $5,988 |
Budget for the step. Many households building a home also pay rent until they move in, so cash flow is tightest in the last months of the build, and the P&I step arrives just as the rent stops. Our guide to the interest-only to P&I switch models the jump for other loan sizes.
Paid or capitalised: which costs more?
Most residential construction loans require you to pay the interest each month. Some lenders, more often on investment, commercial and development loans, will capitalise it instead: the interest is added to the balance and you pay nothing during the build.
Capitalising helps cash flow but costs more, because each month's interest itself earns interest. In the example, capitalised monthly, interest over the 11 months totals about $37,457 instead of $36,575, so the balance at completion is about $937,457 rather than $900,000. The extra $882 is interest on interest.
The bigger issue is room in the limit. Capitalised interest has to fit inside the loan limit, and the lender counts it when testing the LVR, so a capitalised loan needs either a larger limit or a larger contribution from you.
| Point | Interest paid monthly | Interest capitalised |
|---|---|---|
| Cash you pay during the build | $36,575 over 11 months | Nil |
| Balance at completion | $900,000 | About $937,457 |
| Total interest during the build | $36,575 | About $37,457 |
| Effect on LVR | None | Higher by the capitalised amount |
What does a late stage cost?
Delays are where construction interest surprises people. Suppose wet weather and a trade shortage push lock-up back three months. Every draw after frame moves three months later, and for those three extra months you pay interest on the $540,000 balance: 3 × $3,150 = $9,450. If you are renting while you wait, add the rent: at an example $650 a week, 13 weeks costs $8,450. The delay costs about $17,900 before anything else goes wrong.
Other holding costs to price: council rates and insurance on the site, storage, and the maximum construction period in your loan contract. If the house is not finished by then, the lender may want an extension request, a fresh inspection or a fee, and some loans convert to P&I on that date regardless.
A fixed-price contract usually allows the builder extra time for weather and variations, so it does not protect you from holding costs. Read any liquidated damages clause, which may pay you a daily amount for delay the builder causes, and compare it with your daily interest and rent.
How do rate changes affect construction interest?
Most construction loans are variable during the build. The RBA's cash rate target was 4.60% from 30 September 2026, after a 0.25 percentage point increase, and the RBA's 2026 meeting schedule has Monetary Policy Board decisions on 3 November and 8 December 2026. Check the current target before relying on any figure here; lenders set their own construction rates and do not always move in step.
Because build interest is proportional to the rate, the effect is simple to estimate. In the example, a rate 0.25 percentage points higher for the whole build lifts interest from $36,575 to about $37,881, roughly $1,306 more. Our table of how a 0.25% rate rise changes repayments shows the effect after completion, by loan size.
Serviceability is tested on the finished loan, not the first draw. Banks assess repayments at a rate at least 3 percentage points above the loan rate, the buffer APRA kept on 28 May 2026. In the example, $900,000 assessed at 10.0% over 30 years is about $7,898 a month - the figure your income must support, even though your first interest bill is $1,925.
How can you keep construction interest down?
- Pay the deposit and early costs from your own funds where you can, so they never sit on the loan. In the example, paying the $30,000 deposit in cash saves $30,000 × 0.07 × 11 ÷ 12 = $1,925.
- Use an offset account linked to the construction loan if the lender allows one during the build.
- Choose a builder with a realistic timeline, and ask how they handle weather and trade delays.
- Avoid mid-build variations; each one can add cost and time.
- Line up the final inspection and occupancy paperwork early, so the P&I switch and moving in happen together.
- Budget the rent overlap and the P&I step before you sign, not after.
When you have the contract and its payment schedule, post one construction loan request on ADS and 200+ verified lenders and brokers can ask about it. Rates in this post are examples only and are not an offer of credit.
Frequently asked questions
Do you pay interest on the full construction loan amount?
No. Interest is charged only on the amount drawn so far, plus any land loan rolled in at the start. In our example, monthly interest starts at $1,925 after the deposit draw and reaches $5,250 only when the final $90,000 is paid at practical completion.
Are construction loans interest-only during the build?
Usually, for residential construction. You pay interest on the drawn balance each month, and the loan converts to principal and interest at completion unless you have arranged a further interest-only period. Some investment, commercial and development loans capitalise the interest instead.
How much does a construction delay cost in interest?
Roughly the monthly interest on the balance at the time of the delay, multiplied by the months lost. In our example, a three-month delay at frame stage on a $540,000 balance at 7.0% costs $9,450, plus rent or other holding costs while you wait.
When do principal and interest repayments start on a construction loan?
Typically after the final draw at practical completion, or at the end of the construction period in the loan contract if the build runs over. Check both dates in your loan documents, because some loans convert on the end date even if the house is unfinished.
Why is my construction loan interest higher than I expected?
Usually for one of four reasons: interest on the land loan runs from day one, not from the first build draw; the build took longer than planned; the rate rose during construction; or variations added draws. Progress inspection fees are charged separately and add to the cost. Check each against the payment schedule in your contract.
Can I use an offset account during construction?
Some lenders allow one during the build and some only after the loan converts at completion. If yours does, cash held in the offset reduces the balance interest is charged on, which matters most in the later stages when the drawn balance is highest.
Related reading
- Construction Loans: How Progress Payments Work
- Interest-Only to P&I: Modelling the Payment Jump
- Daily Interest Accrual vs Monthly Charging
Sources
- Cash rate target (4.60% effective 30 September 2026) — Reserve Bank of Australia
- 2026 Monetary Policy Board meeting dates — Reserve Bank of Australia
- APRA maintains macroprudential settings: 3 percentage point serviceability buffer (28 May 2026) — Australian Prudential Regulation Authority
- Mortgage calculator — ASIC Moneysmart
Rates checked as at 24 October 2026. Interest rates, lender policies and government schemes change frequently. Figures in this article are illustrative and were accurate at the date shown.
General advice warning: This article contains general information only. It does not take into account your objectives, financial situation or needs, and it is not personal credit or financial advice. Consider whether it is appropriate for you and seek advice from a licensed credit representative before acting.
Any interest rate shown is an example only and is not an offer of credit. Where a rate is quoted, the applicable comparison rate is available from the relevant lender and should be considered alongside it.
Tags
Related Posts
Bridging Loans Worked Through: Peak Debt, End Debt and Capitalised Interest
A bridging loan lets you buy before you sell. The numbers that matter are peak debt (what you owe while you hold both properties), the sale proceeds after selling costs, the end debt left once the...
If Rates Fall to 3%: The Refinancing Window Modelled
If Rates Fall to 3%: The Refinancing Window Modelled is best assessed as a decision framework rather than a headline promise. Define the purpose, compare total cost and flexibility, test the downsi...
Effective Rate on Merchant Cash Advances (Factor Rates Decoded)
Effective Rate on Merchant Cash Advances (Factor Rates Decoded) is best assessed as a decision framework rather than a headline promise. Define the purpose, compare total cost and flexibility, test...